Table of Contents
Key Takeaways
- When your car is totaled, the insurance company compares the cost of repairs to the car’s actual cash value, which includes factors like mileage, condition, and depreciation, which is wear, tear, and prior damage.
- An insurance adjuster or appraiser uses comparable used car listings in your zip code to help estimate the value of the vehicle, and reviewing these details can help you spot mistakes in the valuation.
- If the at-fault driver’s insurance company accepts liability, their liability coverage may pay for your damaged vehicle, rental needs, and other property losses tied to the motor vehicle crash.
- Your car insurance policy may still play a role in the insurance claim, especially if your insurer steps in first and later seeks repayment from the at-fault party through subrogation.
- A lawyer at Marcari, Russotto, Spencer & Balaban can help you understand whether the settlement amount reflects the actual cash value of your car and explain your options if the insurer undervalues your damaged vehicle or delays communication.
After an auto accident, it can be stressful to learn that your car has been declared a total loss, especially when you did nothing to cause the crash. You may be wondering how you will get to work and/or doctor’s appointments, what your insurance policy actually covers, and whether the payout will match the value of your vehicle. Without reliable support, people sometimes accept an offer that does not accurately reflect what their actual cash value of their car was before the accident.
At Marcari, Russotto, Spencer & Balaban, we support drivers across Virginia, North Carolina, and South Carolina who are dealing with a not-at-fault total loss. It can be confusing to sort through insurance rules and valuation questions on your own, so our car accident lawyers can step in to explain how the process works and address concerns as they come up. We talk directly with the insurer, review how they calculated your vehicle’s value, and help you pursue the payment available under your coverage and state law.
How Insurers Decide When a Car Is a Total Loss
A car is considered a total loss when the repair cost is higher than what it was worth before the accident. Some states also use a set percentage of the vehicle’s value, known as a total loss threshold, to decide when repairs are no longer practical.
Insurance companies may declare a total loss when:
- Repair costs exceed the vehicle’s fair market value
- The frame or key safety systems cannot be restored
- The state’s total loss threshold, often around 70% to 75%, is met
Each state has its own rules for total loss valuations, and insurers are expected to follow those standards when evaluating a claim.
Insurance Coverage That Applies When Your Car Is Totaled
Depending on your policy, several types of coverage may apply when a car is declared a total loss:
- Collision coverage pays for damage to your vehicle after a crash, regardless of who caused the accident.
- Comprehensive coverage applies when the loss results from theft, weather, fire, or another non-collision event.
- Property damage liability from the at-fault driver’s insurer typically covers your losses when another person caused the crash.
- Uninsured Property Damage (UMPD) pays for damages to your vehicle after a crash when the party at fault is uninsured.
- Underinsured Property Damage (UIMPD) pays for damages to your vehicle after a crash when the party at fault does not have enough coverage.
If you were not at fault, the other driver’s insurance usually pays for your vehicle damage. In some cases, your insurer may handle the claim first and then seek reimbursement through subrogation.
Should I Contact a Lawyer After a Total Loss Accident?
If you are dealing with delays, valuation disagreements, or communication issues with the insurance company, speaking with a car accident lawyer can help you understand your options. At Marcari, Russotto, Spencer & Balaban, our team reviews the details of your claim, communicates with the insurer, and helps you pursue the payment available under your coverage and state law. This support can ease stress and give you a clearer path forward.
Why Clients Turn to Marcari, Russotto, Spencer & Balaban
Marcari, Russotto, Spencer & Balaban has spent years helping drivers across Virginia, North Carolina, and South Carolina navigate the challenges that follow a total loss accident. Our team is known for steady communication, careful review of insurance valuations, and a commitment to guiding clients through each step with clarity. We take the time to explain how state laws shape the claims process, what your policy covers, and what to expect as your claim moves forward.
By staying accessible and focused on your concerns, we work to ease the stress of dealing with an unexpected loss and support you as you pursue the payment available under your coverage and state law.
Testimonials
“I had a wonderful experience with this law firm. They were excellent at communication at keeping me in the loop with everything about my personal injury case. I’d highly suggest anyone needing a lawyer due to a car accident to come to this firm.” — Landon Z.
“The services rendered from Marcari and Associates were excellent. I recommend the Lynder and Attorney Spencer to anyone needing legal advice for accidents and other services.” — Juanita B.
“After my accident I was paired with attorney Savannah Parker and paralegal Ashley. They were an incredible team and fought hard for me. Not knowing what to expect, every question was answered and I was informed with every update. It was an amazing experience that I am extremely grateful for. Absolutely recommended!” — Daniel R.
What Should I Do if My Car Is Totaled and I’m Not at Fault?
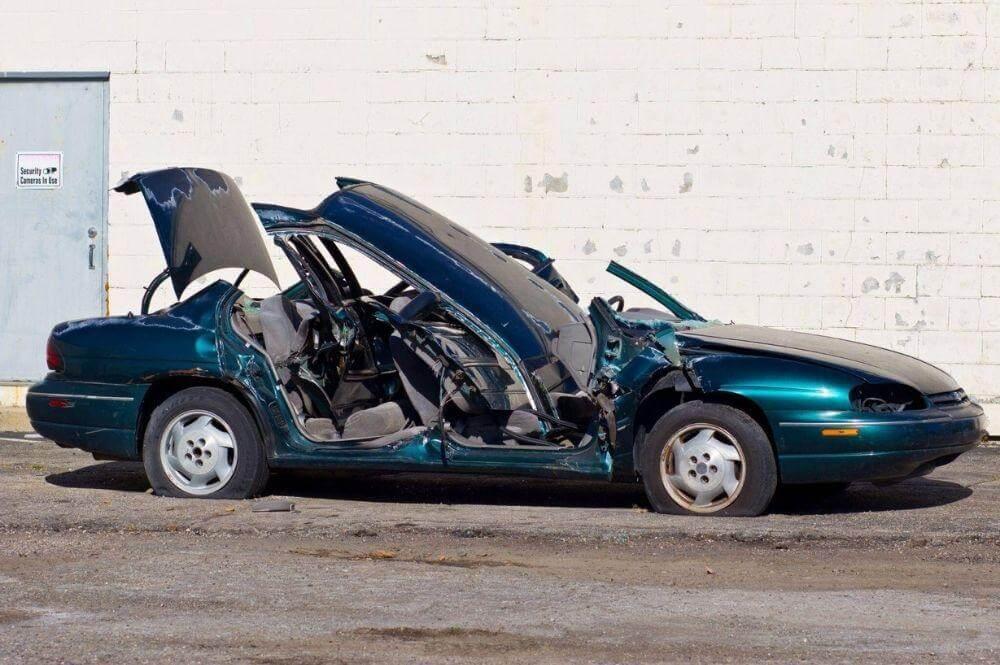
If your car is totaled and you were not at fault, taking a few early steps can help keep the process on track:
- Get a copy of the police report so you have documentation of how the crash occurred.
- Notify your insurer and the at-fault driver’s insurer.
- Collect photos, receipts, and other records that show the vehicle’s condition and value before the accident.
- Remove personal items and your license plates once the vehicle has been declared a total loss.
- Look over all settlement offers carefully and ask questions if anything seems unclear.
A car accident lawyer at Marcari, Russotto, Spencer & Balaban can explain your legal options and provide support as you move through the claim.
Total Loss Rules in Virginia, North Carolina, and South Carolina
Virginia
Virginia’s 75% rule shows up in the salvage-title process. Under Va. Code § 46.2-1602.1, when an insurer acquires a qualifying vehicle through the claims process, it must apply for the proper salvage or nonrepairable title when the estimated repair cost is more than 75% of the vehicle’s actual cash value, as defined in Va. Code § 46.2-1600.
North Carolina
North Carolina treats a vehicle as a total loss when repair costs reach the 75% mark. Under 11 NCAC 04 .0418, if the cost to repair equals or exceeds 75% of the vehicle’s pre-accident actual cash value, the claim is handled as a total loss. That rule also states that, if the owner requests it, the insurer must provide written documentation explaining how the total loss payment amount was calculated.
South Carolina
South Carolina’s total loss threshold is defined by statute. Under S.C. Code Ann. § 56-19-480(G), a vehicle is considered a total loss when the cost to repair (parts and labor) equals or exceeds 75% of the vehicle’s fair market value. In practice, insurers may still declare a total loss in some situations even when damage is below 75%, depending on the vehicle and the title process being used.
How Insurance Companies Calculate the Value of a Totaled Car
Insurance companies start by calculating the actual cash value, or the car’s ACV, which reflects what your vehicle was worth immediately before the accident. This number comes from several details, including the car’s age, mileage, condition, and any factory- or dealer-installed features. Insurers also review comparable vehicle listings in your area to estimate a fair market range.
After the ACV is set, the insurer compares that amount to the repair estimate. This comparison determines whether the vehicle meets the criteria for a total loss under your state’s rules.
Checking the Accuracy of Your Valuation Report
When you receive the valuation report, it helps to review the details closely. Even small errors can affect the final number. Verify that:
- The trim level and listed features match your vehicle
- The mileage and condition are accurate
- The comparable vehicles come from your area and include similar equipment
- Required taxes and fees are included in the calculation
If anything looks incorrect, you can point it out and request an updated report.
Correcting Errors in Your Total Loss Valuation
Valuation reports can sometimes include mistakes, and correcting those issues can help you obtain a more accurate number. If something in the report does not match your records, you can gather helpful documentation such as:
- Recent photos and maintenance receipts
- Comparable listings from nearby dealerships
- Proof of recent repairs or added features
Share this information with the adjuster and ask for the valuation to be updated. Providing clear documentation often helps resolve concerns about the vehicle’s value.
Who Covers the Costs After a Total Loss?
When another driver is at fault, their insurance company is typically responsible for covering your property damage. This may include:
- The actual cash value of your totaled vehicle
- Sales tax, title fees, and registration costs, based on your policy and state rules
- Towing and storage expenses
- A rental car or reimbursement for loss of use
If the at-fault driver does not have enough insurance, your own uninsured motorist coverage or collision coverage may help cover the remaining costs under your policy.
How Deductibles and Subrogation Affect Your Total Loss Claim
You can choose to file the property damage claim through your insurance company, even when the other driver was at fault. Your insurer may handle the payout first and then seek reimbursement from the at-fault driver’s insurance through a process called subrogation. If your insurer later recovers the full amount, your deductible may be returned to you.
If you want an update during the process, you can ask your adjuster about the current status of the subrogation claim.
Understanding Your Insurance Payout After a Total Loss
Insurance companies generally pay the actual cash value of your vehicle based on its condition right before the accident, minus your deductible if the claim goes through your own policy. If you choose to keep the vehicle, the insurer subtracts the salvage value from your payment, and the title will be changed to a salvage title.
Most insurers do not include the value of the car with aftermarket additions unless you have documentation showing those upgrades and your policy provides coverage for them. Some loans will not allow you to retain your vehicle unless you pay off the loan in full first.
How Loans and GAP Coverage Affect a Total Loss Payout
If your vehicle has a loan, the insurance payout is sent to the lender first. If the payment does not cover the full balance, gap coverage may help pay the remaining amount, depending on the terms of your policy. If you want to keep the vehicle, you can ask to retain it, but the insurer will subtract the salvage value from your payout, and the title will be changed to a salvage title.
What to Do When You Disagree With a Total Loss Valuation
If the valuation does not reflect what you believe your vehicle was worth, you can take steps to address the issue:
- Gather documentation that supports a higher value, such as local comparable listings, maintenance records, or proof of recent repairs.
- Ask the adjuster to take another look at the valuation using the updated information.
- If the disagreement continues, you may file a complaint with your state’s Department of Insurance or speak with a car accident lawyer for guidance.
Marcari, Russotto, Spencer & Balaban can review your valuation report, explain where the numbers may be falling short, and help you understand the options available under your policy and state law. Having clarity during this stage often makes the next steps feel more manageable.
What Happens if My Insurance Payout Does Not Cover My Car Loan?
If the amount you still owe on your car loan is higher than the insurance payout, you are responsible for the remaining balance. Gap insurance may help cover this difference by paying the remaining amount owed to your lender, depending on the terms of your policy.
If you are unsure how the payout will interact with your loan or gap coverage, a car accident lawyer can explain your options and help you understand what the next steps may look like.
What to Do if Your Car Was Worth More Than the Insurance Estimate
If you believe your car was worth more than the amount listed in the insurer’s valuation, you can gather documentation that reflects the vehicle’s true condition. Helpful information may include lower verified mileage, recent service records, or comparable vehicle listings that show a higher market value. Sharing these details with the adjuster gives them a clearer picture of your vehicle and may lead to a revised valuation.
Can I Keep My Car After It’s Declared a Total Loss?
Yes. You can request to keep your vehicle after a total loss decision. The insurer will subtract the salvage value from your payout, and the title will be changed to a salvage title according to state requirements.
Understanding Salvage and Branded Titles After a Total Loss
If you decide to keep your totaled vehicle, state laws generally require the title to be marked as salvage or non-repairable. Before the car can return to the road, it must pass a required inspection to confirm that the repairs meet state standards. Some insurance companies offer limited coverage for vehicles with salvage titles, so it is helpful to ask your insurer about available options if you plan to keep and repair the vehicle.
How Long Does It Take to Get Paid for a Totaled Car?
The timeline for a total loss payment varies based on how quickly liability is determined and how long it takes to complete the valuation. The process often includes:
- Confirming who was at fault
- Completing the vehicle valuation
- Finalizing the total loss decision
- Sending payment to any lienholder, if you have a loan
- Releasing the remaining funds to you
- Completing any title or salvage steps required by the state
A car accident lawyer at Marcari, Russotto, Spencer & Balaban can help by reviewing delays in the process, communicating with the insurer on your behalf, and explaining what to expect at each stage so you have a clearer understanding of the timeline.
Can a Total Loss Claim Affect Your Future Insurance Rates?
A total loss claim can sometimes influence what you pay for car insurance in the future, even when you did not cause the accident. Some insurers review your overall claims history when renewing a policy, which may lead to changes in your premium. It can help to look over your policy, ask your insurer how this type of claim may be treated, and learn whether your plan offers options such as accident forgiveness.
If you have questions about how the claim process works or what to expect as you move forward, the team at Marcari, Russotto, Spencer & Balaban can explain your options and provide legal guidance during this part of the process.
Frequently Asked Questions About Total Loss Claims
How Can I Get a New Car After a Total Loss?
Once the insurance payout is issued, you can use those funds toward purchasing another vehicle. If you had a loan, the insurer will pay the lender first and then send any remaining balance to you.
Can I Get Compensation for Personal Items That Were Damaged or Lost in the Crash?
Many auto insurance policies offer limited coverage for personal belongings that were damaged inside the vehicle. You may need receipts, photos, or other records to support your claim. If you have questions about whether your items are covered or how to document them, the team at Marcari, Russotto, Spencer & Balaban can help you understand what your policy allows.
What if the Insurance Company Is Not Responding or Keeps Delaying My Total Loss Claim?
Insurance delays can happen when there are questions about liability, valuation, or documentation. You can request a status update from your adjuster and ask what information is still needed to move the claim forward. If delays continue, a lawyer at Marcari, Russotto, Spencer & Balaban can step in, communicate with the insurer, and help you understand the next steps available under your policy and state law.
What If I Need a Car Longer Than the Rental Period Allows?
The insurer typically covers a rental for a reasonable amount of time, typically 3-5 days after your vehicle has been deemed a total loss.
Find Out How a Total Loss Claim Works and How We Can Help With a Free Consultation
If your car was totaled in an accident you did not cause, you deserve clear guidance and support during the claims process. The team at Marcari, Russotto, Spencer & Balaban helps drivers across Virginia, North Carolina, and South Carolina understand their options, review insurance valuations, and move forward with confidence.
You can reach us at 855-435-7247 or contact us through our online form to schedule a free consultation to discuss your situation with no obligation.

Written By Donald Marcari
Don is the Senior Managing Partner at Marcari, Russotto, Spencer & Balaban. He gained national attention when his exploits as a defense attorney with the U.S. Navy JAG Corps became the basis for “A Few Good Men.”